Real Estate Across Maryland, Pennsylvania, Virginia & West Virginia.
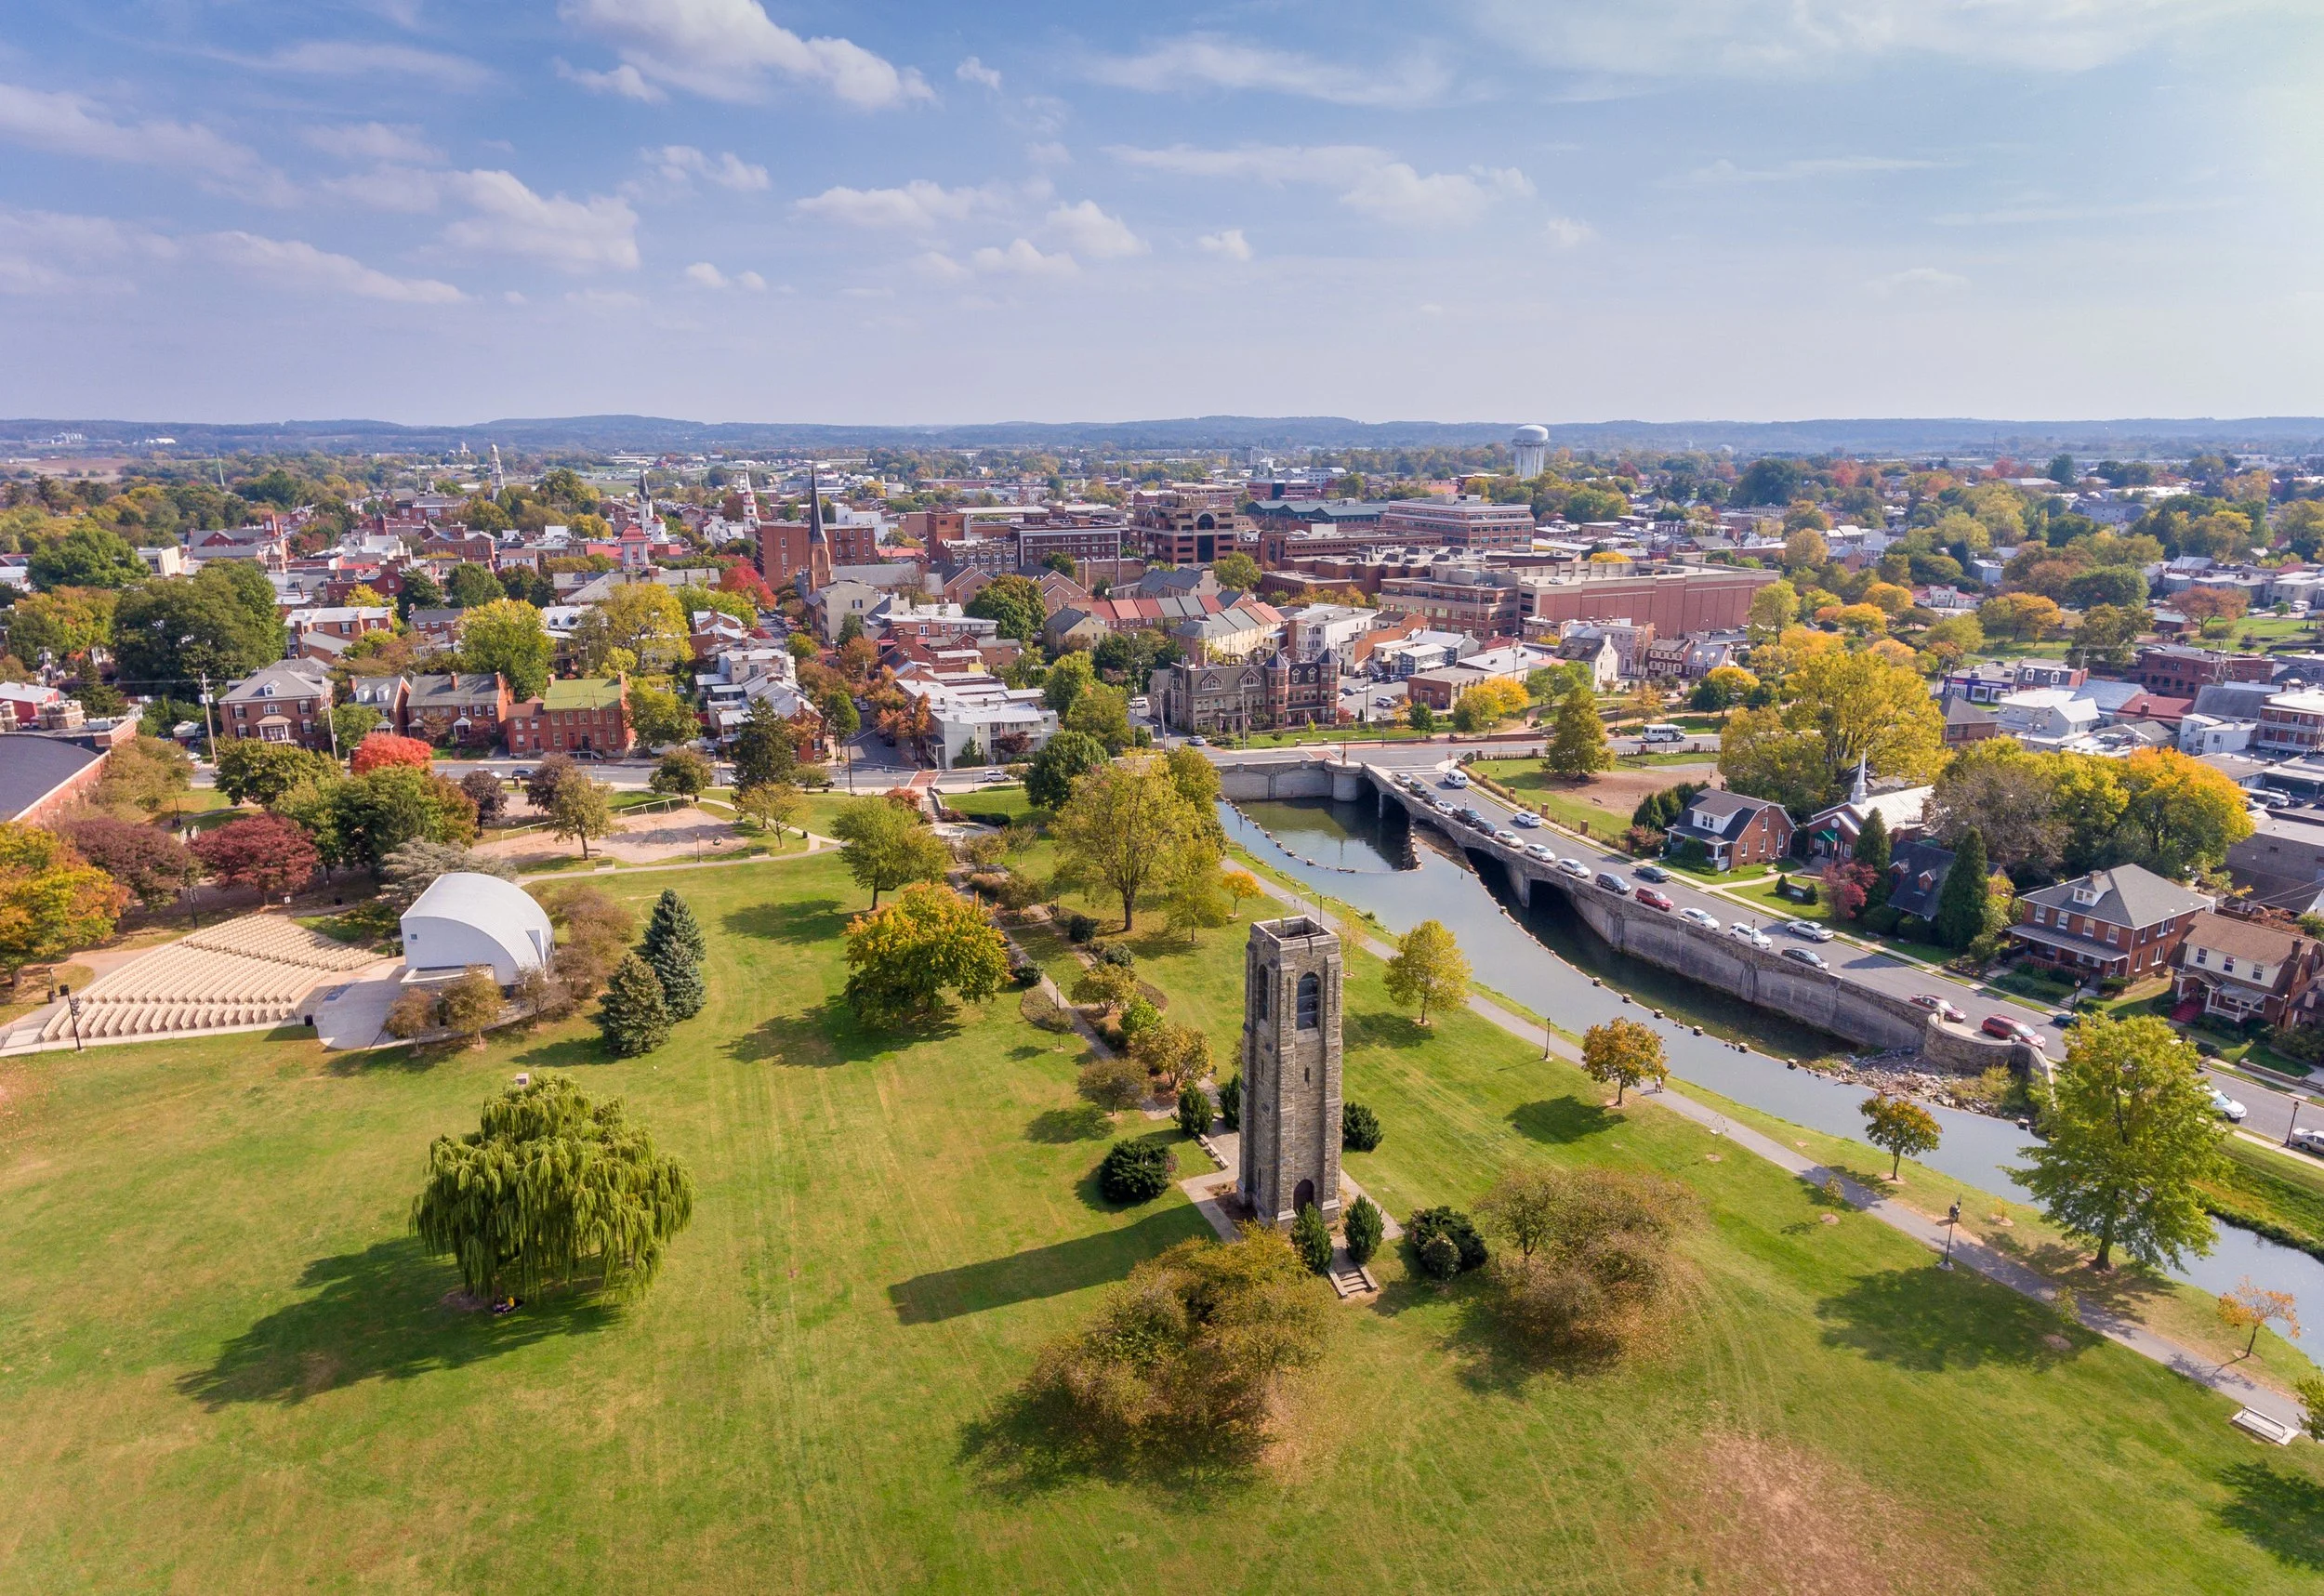
Based in Frederick. Trusted throughout the region.
Based in Frederick. Trusted throughout the region.
WE’VE SOLD OVER
WE SELL A HOME EVERY
OUR LISTINGS SELL FOR
OF FINAL LISTING PRICE
WHY BUY WITH
Because anyone can open a door…even a monkey. You need a Professional. An adviser who can guide you through each step. A town expert, who can give you the inside on the local insight. A fighter who will go to battle for you to get you the absolute best (and won’t settle for any less). Arming you with the best information, giving you confidence in every decision. To get you the best price, on that perfect place. We save our buyers over $12,500 off list price. We help our buyers win offers, enjoy the experience, and find that place that they call home.
The housing market changes quickly. Rates move, inventory shifts, new laws take effect, and the headlines don't always tell the whole story.
We follow what's happening and break down what it actually means for homeowners, buyers, and sellers across our market.
Should You Buy a Home Now or Wait for Mortgage Rates to Drop?
If you've been waiting for mortgage rates to come down before buying a home, you're certainly not alone. Over the past few years, higher borrowing costs have pushed plenty of potential buyers to the sidelines, hoping that a lower interest rate will make homeownership more affordable. And with the possibility of mortgage rates moving lower, it's understandable why some buyers are thinking about waiting just a little longer.
But there's something I think more people should be considering: What happens to home prices and competition when those lower rates finally arrive? Because while a lower mortgage rate might make your monthly payment more attractive, it could also bring a wave of buyers back into the market. And that could change the negotiating power buyers have right now.
Today's Market May Offer Buyers Something They Haven't Had in Years
For much of the pandemic-era housing boom, buyers were competing against multiple offers, waiving contingencies, and sometimes paying significantly more than the asking price just to get a home under contract. That environment has changed in many markets.
Higher mortgage rates have reduced affordability, and some homes are taking longer to sell. Sellers who initially priced their properties too aggressively are finding that buyers aren't necessarily willing to pay whatever they're asking.
As a result, we're seeing opportunities for buyers to negotiate that simply weren't available when competition was at its peak. Depending on the property and local market conditions, buyers may be able to negotiate a lower purchase price, request closing cost assistance, or ask sellers to address repairs before settlement.
Those opportunities aren't available with every home, of course. Well-priced properties in desirable locations can still attract significant interest. But buyers today may have more room to negotiate than they realize.
What Happens When Mortgage Rates Drop?
Let's say mortgage rates fall enough to convince a large number of buyers that it's finally time to make a move. Those buyers start scheduling showings, attending open houses, and making offers. Homes that might have attracted one or two interested buyers suddenly have several.
When more buyers compete for the same inventory, sellers generally gain negotiating power. Price reductions may become less common, sellers may be less willing to offer concessions, and buyers could find themselves competing against multiple offers again.
That doesn't mean a drop in mortgage rates will automatically send home prices soaring. Inventory, employment, local economic conditions, and the pace of rate changes all play important roles. But it does mean that waiting for a lower interest rate isn't necessarily the same thing as waiting for a better deal.
A Lower Interest Rate Doesn't Always Mean a Better Purchase
Consider a hypothetical example involving a home priced at $500,000.
A buyer purchasing in today's market might negotiate the price down to $480,000 and potentially receive some seller assistance with closing costs.
Another buyer decides to wait until mortgage rates fall. By the time that happens, more buyers have entered the market, and the same home attracts enough competition to sell for $510,000.
Even though the second buyer secures a lower mortgage rate, they're also paying $30,000 more for the property. That higher purchase price affects the down payment, the amount financed, and potentially the buyer's long-term equity position.
Now, that doesn't mean the first buyer automatically comes out ahead. The actual financial difference depends on the interest rates, loan terms, closing costs, and how long each buyer owns the home. The point is that the interest rate is only one part of the equation. The price you pay for the home matters, too.
What About Buying Now and Refinancing Later?
You've probably heard the phrase "marry the house, date the rate." The idea is that you can purchase a home now and refinance your mortgage if interest rates come down in the future. There's some logic behind that strategy, but I think it's important to be realistic about it.
Refinancing isn't guaranteed, and it isn't free. You'll generally need to qualify for a new loan, your home's value and equity position can affect your options, and refinancing may involve additional closing costs. More importantly, nobody can promise when mortgage rates will fall or how far they'll go.
If you're buying a home today, you should be comfortable with the monthly payment you're agreeing to now, not one you're hoping to have two years from now. If rates eventually decline enough to make refinancing worthwhile, that could be an added benefit. But it shouldn't be the only reason you can afford the home.
The Right Time to Buy Depends on More Than the Market
I talk to buyers all the time who want to know whether they should purchase now or wait six months, a year, or even longer. And the answer isn't always the same.
If you're financially prepared, have stable income, plan to stay in the home for several years, and can comfortably afford the payment, today's market may offer opportunities worth exploring. On the other hand, if purchasing would stretch your budget too far, you don't have adequate savings, or you're uncertain about your future plans, waiting may be the smarter financial decision.
The key is understanding your options rather than making a decision based entirely on where you think mortgage rates might be headed. And remember, real estate is local. The opportunities available in Frederick County may be very different from those in Montgomery County, Northern Virginia, or the Eastern Panhandle of West Virginia. Even neighboring communities can have very different inventory levels, buyer demand, and pricing trends. That's why a local market analysis matters much more than a national headline.
Don't Just Watch Mortgage Rates. Watch the Opportunities.
There's nothing wrong with wanting a lower interest rate. Even a modest reduction can make a meaningful difference in your monthly mortgage payment. But while you're watching rates, it's worth paying attention to what's happening with home prices, inventory, and seller concessions. The best opportunity to buy may not come when mortgage rates hit a particular number. It may come when you find the right home, at the right price, with terms that make sense for your financial situation.
If you've been sitting on the sidelines waiting for rates to drop, let's take a look at what's actually available in your market. You might be surprised by the negotiating opportunities that exist right now.
At The Krop Team, we help buyers throughout Maryland, Pennsylvania, Virginia, West Virginia, and Washington, D.C., understand their options and make informed decisions. Whether you're ready to purchase today or just beginning to explore the possibility, we'd be happy to help you develop a strategy that works for you.
November Real Estate Market Update: Lower Rates, Price Reductions, and Opportunities for Buyers
As we head into the final stretch of 2026, the real estate market is giving us plenty to talk about. Mortgage rates may finally be moving in a more favorable direction, sellers are becoming more realistic about pricing, and buyers who are willing to shop during the holiday season could find themselves in a stronger negotiating position than they might expect.
There's still plenty of uncertainty in the market, but that doesn't mean people should put their real estate plans on hold. In fact, some of the changes we're seeing could create opportunities for buyers and sellers who understand what's happening and have a good strategy in place.
Let's take a closer look at what's shaping the market this November.
Could Mortgage Rates Finally Fall Below 7%?
Mortgage rates have been one of the biggest challenges facing homebuyers over the past several years. Higher borrowing costs have stretched monthly budgets, reduced purchasing power, and caused many would-be buyers to delay their plans.
Now, we're beginning to see signs that rates could make their way back below 7%. That's certainly encouraging news, although there's no guarantee that rates will continue moving downward.
Even relatively small changes in mortgage rates can make a meaningful difference in affordability. For example, on a $400,000 mortgage, the difference between a 7.5% interest rate and a 6.75% rate is approximately $200 per month in principal and interest. Over the course of a year, that's roughly $2,400 in savings.
But there's another side to the conversation that buyers need to consider. What happens when mortgage rates drop and more buyers decide it's time to get back into the market?
We've seen how quickly competition can increase when borrowing conditions improve. Buyers who have been waiting on the sidelines may begin scheduling showings and submitting offers, potentially putting upward pressure on home prices in desirable neighborhoods.
That's why I encourage buyers to look at the entire picture rather than focusing exclusively on the interest rate. The price you pay for a home, your ability to negotiate, your monthly payment, and your long-term plans all matter. Waiting for lower rates might make sense for some buyers, but it isn't automatically the best financial decision for everyone.
More Price Reductions Don't Necessarily Mean Home Values Are Falling
Another trend worth watching is the number of homes receiving price reductions.
Nationally, a substantial share of listings have seen asking-price adjustments, reflecting a market where buyers are more selective and sellers can't always command the prices they could a few years ago. But there's an important distinction here: a price reduction doesn't necessarily mean a home has lost value.
In many cases, the property was simply listed too high to begin with.
During the height of the seller's market, homeowners became accustomed to seeing properties sell quickly, sometimes with multiple offers and very little negotiation. That environment encouraged aggressive pricing, and some sellers are still approaching the market with those expectations.
Today's buyers are behaving differently. They're comparing properties, paying close attention to condition, evaluating monthly ownership costs, and taking more time to decide whether a home is worth its asking price.
When a property enters the market at an unrealistic price, buyers may simply pass it over. The home sits, showing activity slows, and eventually the seller makes a reduction to generate renewed interest. The problem is that by the time the price is adjusted, the listing may have already lost some of the momentum that comes with being new to the market. For homeowners thinking about selling, this is why getting the price right from day one is so important.
A strong pricing strategy doesn't mean giving your home away or automatically listing below market value. It means understanding what comparable properties are actually selling for, evaluating the competition, and positioning your home to attract serious buyers. Homes that are priced appropriately, presented well, and marketed effectively can still perform very well. Sellers just need to recognize that the strategy that worked in 2021 or 2022 may not be the strategy that works today.
Why November Could Be an Overlooked Opportunity for Homebuyers
Most people associate spring and early summer with buying a home. The weather is better, school schedules make moving easier, and there are typically more properties coming onto the market. But there's something to be said for buying when everyone else isn't.
As we move into November and the holiday season, real estate activity often slows. Families become busy with Thanksgiving, Christmas, travel, and year-end commitments. Some buyers decide to wait until spring, which can leave fewer people actively competing for available homes.
For buyers who are ready to make a move, that seasonal slowdown can work in their favor. With less competition, buyers may have more time to evaluate properties, arrange inspections, and negotiate terms without feeling the same pressure they might experience during the spring market.
Sellers who keep their homes listed through the holidays may also have specific reasons for wanting to move. Job relocations, family changes, financial considerations, and plans to purchase another property don't necessarily follow the traditional real estate calendar. That doesn't mean every seller is desperate or that every listing will come with a substantial discount. It does mean that buyers may find opportunities to negotiate on price, closing costs, repairs, or other contract terms.
There's also a potential advantage to purchasing before mortgage rates fall further. If lower rates eventually bring more buyers back into the market, some of the negotiating flexibility available today could disappear. Of course, there is a tradeoff. Inventory is often more limited during the winter months, so buyers may have fewer homes to choose from. But for someone who finds the right property, November and December can be excellent times to make a move.
What Does This Mean for Sellers Heading Into the Holidays?
If you're considering selling your home, you might be wondering whether it's better to list now or wait until spring. The answer depends on your property, your circumstances, and the competition in your local market. It's true that buyer activity typically slows during the holidays,
How Overpricing Your Home Can Cost You Thousands (And Why Pricing It Right From Day One Matters)
When you're getting ready to sell your home, it's natural to want the highest price possible. After all, you've invested years of mortgage payments, maintenance, improvements, and probably a fair amount of sweat equity into the property. You want to make sure you're getting everything it's worth.
That's why one of the most common conversations we have with sellers involves their asking price. Some homeowners want to list a little higher than the market suggests, figuring they can always come down later if they need to. Others believe starting high gives them more room to negotiate.
I understand the thinking, but there's a problem with that strategy. Overpricing your home can actually cost you money, sometimes thousands of dollars, and the longer it sits on the market, the harder it can become to recover.
Your First Few Weeks on the Market Matter More Than You Think
When a home first hits the market, it typically receives its greatest burst of attention. Buyers who have been searching for weeks or months see a new listing pop up, agents share it with their clients, and people schedule showings to see whether it's the right fit.
That initial exposure is valuable because you're reaching buyers who are already actively looking for a home like yours. But if your home is priced significantly higher than comparable properties, many of those buyers may never schedule a showing. Some will assume it's overpriced based on the photos and details, while others won't even see it because their online searches have maximum price limits.
For example, imagine your home is realistically worth around $500,000, but you decide to list it at $550,000 to leave some negotiating room. Buyers searching up to $525,000 may never see your listing, even though they could be exactly the people most interested in purchasing it.
By the time you reduce the price, some of those buyers may have already purchased something else.
The Longer Your Home Sits, the More Questions Buyers Ask
Buyers pay attention to how long a property has been listed. When a home has been sitting on the market longer than similar properties in the neighborhood, people naturally start wondering why.
Is something wrong with the house? Has an inspection uncovered a problem? Is the seller difficult to negotiate with? Sometimes the answer is simply that the home was overpriced from the beginning. Unfortunately, buyers don't always know that.
A home that might have generated strong interest at the right price can begin to feel less desirable after several weeks or months on the market. And when buyers sense that a seller is struggling to attract offers, they may become more aggressive in their negotiations. That can mean lower offers, requests for closing cost assistance, or additional concessions that ultimately reduce what the seller walks away with.
Here's How Overpricing Can Cost You Thousands
Let's look at a hypothetical example.
Two similar homes have an estimated market value of $500,000.
Seller A lists at $499,900, generating strong interest from buyers who recognize that the home is competitively priced. With good presentation and marketing, the property attracts multiple showings and sells for $505,000.
Seller B decides to test the market at $540,000. Showings are limited, and after several weeks, the seller reduces the price to $525,000. Eventually, another reduction brings it to $499,900, but by then the listing has accumulated significant time on the market. A buyer offers $485,000, and the seller accepts.
That's a $20,000 difference between two otherwise similar properties.
Of course, this is an illustration, not a guarantee of what will happen in every transaction. Market conditions, property condition, competition, and buyer demand all influence the outcome. But it demonstrates why starting with an inflated price can be a costly gamble.
And the sale price isn't the only consideration. Additional mortgage payments, utilities, insurance, maintenance, and carrying costs can add up while a property sits unsold, particularly if the seller has already moved into another home.
Pricing Your Home Right Doesn't Mean Pricing It Low
This is probably the most important distinction I want homeowners to understand. When we recommend a competitive listing price, we're not suggesting that you leave money on the table. We're trying to position your property to attract the strongest possible buyer interest and give you the best opportunity to maximize your return.
There's a big difference between pricing a home strategically and simply choosing a low number. A good pricing strategy considers recent comparable sales, current competing listings, the condition of your home, its location, and what buyers are actually willing to pay. It also takes into account how quickly similar homes are selling and whether buyers in your particular price range have plenty of alternatives.
And that last part matters. Real estate is local, sometimes down to the neighborhood or even the street. What's happening in Frederick may look different from what's happening in Hagerstown, Martinsburg, or Northern Virginia. That's why relying on a national headline or an automated home valuation isn't enough to determine the best asking price.
What If Your Home Is Already Overpriced?
If your home has been on the market longer than expected, it doesn't necessarily mean you've missed your opportunity to sell. But it may be time to reevaluate your strategy.
The first step is looking at what the market is telling you. Are buyers scheduling showings but not making offers? Are you getting very little activity at all? Have similar homes sold while yours remains available?
Each situation tells us something different. Sometimes the issue is price. Other times, it may involve photography, presentation, property condition, showing availability, or the way the home is being marketed. In many cases, it's a combination of factors.The important thing is to make adjustments based on actual market feedback rather than continuing to wait and hope that the right buyer eventually comes along.
The Goal Isn't the Highest Asking Price. It's the Best Selling Price.
I always remind sellers that the number we put on the listing isn't necessarily the number they'll receive at closing. Anyone can suggest a high asking price. The real value of an experienced real estate agent is understanding how to position your home so that buyers recognize its value, take it seriously, and are motivated to make an offer.
Sometimes that means pricing right at market value. Sometimes the best strategy is slightly above or below it, depending on the property and the competition. What matters is having a reason behind the number rather than choosing a price simply because it's what you'd like to receive.
If you're considering selling your home in Frederick County or anywhere throughout Maryland, Pennsylvania, Virginia, West Virginia, or D.C., we'd be happy to help you understand what your property could realistically sell for in today's market.
Before you choose an asking price, let's look at the numbers together. A smart pricing strategy from day one could make a significant difference in what you ultimately walk away with.
Some of the Best Real Estate Deals Right Now Might Be in New Construction
If you've been putting off buying a home because of mortgage rates, there's an opportunity you might be overlooking: new construction.
When most people think about buying a brand-new home, they assume it's going to cost more than purchasing an existing property. And while that can certainly be true, something interesting is happening in the housing market right now. Some of the biggest homebuilders are offering incentives that could make buying a new home more affordable than buyers realize.
The reason is pretty simple. Builders have homes they need to sell, and an empty, completed home isn't making them any money.
Why Builders Are Motivated to Make Deals
Unlike individual homeowners, large homebuilders are operating a business with construction schedules, inventory, financing costs, and sales goals. When a home is finished and ready for someone to move in, the builder generally wants to get it sold as quickly as possible.
Every month that property sits unsold means additional carrying costs. And when a builder has multiple completed homes sitting in the same community, those costs can add up.
That's where buyers may have an advantage. Rather than letting completed homes sit empty, some builders are willing to negotiate on price or offer financial incentives to get a deal done. And depending on the builder, the community, and the specific home, those incentives can be substantial.
What Kind of Deals Are Builders Offering?
We're seeing several types of incentives in the new construction market, and some can make a meaningful difference in what a buyer pays upfront or over the life of their mortgage.
Price Reductions: Builders may reduce the asking price on completed homes, particularly when they have several properties available or want to close out a phase of a development.
Mortgage Rate Buydowns: This is one of the more interesting opportunities. Some builders are offering to pay upfront costs to secure a lower mortgage interest rate for buyers. Depending on the program, that lower rate might be permanent or temporary. Either way, it's worth exploring because the difference in monthly payments can be significant.
Closing Cost Assistance: Buyers may be able to negotiate thousands of dollars toward closing costs, reducing the amount of cash they need to bring to the table.
Upgrades and Other Incentives: Builders may also offer appliance packages, upgraded finishes, or other extras that would ordinarily cost buyers additional money.
Not every builder is offering all of these incentives, and the best deals often apply to specific homes rather than an entire community. But that's exactly why it's worth doing some homework before ruling out new construction.
The Best Opportunities May Be Homes That Are Already Finished
Here's something buyers should pay particular attention to: quick move-in homes.
These are homes that have already been built, or are nearly finished, and don't have a buyer lined up. Builders often have more flexibility with these properties than they do with homes that haven't been started yet. They've already invested the money into construction, and they're ready to move on to the next sale.
That doesn't mean every completed home is a bargain. But if you're flexible about the floor plan, finishes, or exact lot, you may find an opportunity that wouldn't exist if you were building from scratch.
It's also worth paying attention to builders approaching the end of a sales period or trying to finish selling the remaining homes in a community. Those situations can sometimes create additional negotiating opportunities.
A Lower Interest Rate Isn't Always the Best Deal
One thing I always tell buyers is to look beyond the advertised incentive.
A builder might advertise an attractive mortgage rate, but you need to understand exactly what you're getting. Is that rate fixed for the life of the loan, or does it increase after the first year or two? Are you required to use the builder's preferred lender? Is the home priced competitively compared to similar properties?
A lower interest rate can be a tremendous benefit, but it needs to make sense when you look at the entire transaction. The same goes for closing cost assistance and upgrades. A $15,000 incentive sounds great, but you still need to know whether you're paying a fair price for the home in the first place. That's where having an experienced real estate agent on your side becomes especially important.
Don't Walk Into a Builder's Sales Office Without Representation
One of the biggest misconceptions about buying new construction is that you don't need a real estate agent because the builder already has someone handling sales. What buyers need to understand is that the person working in the builder's sales office represents the builder's interests, not yours.
Having your own agent means having someone who can help evaluate the pricing, compare incentives, negotiate terms, review important contract details, and identify potential issues before you commit. And in many cases, builders already account for real estate agent compensation in their sales structure, although the terms vary.
It's also important to involve your agent before your first visit to a new construction community. Some builders have registration requirements that can affect whether your agent is able to represent you in the transaction.
Don't Let Mortgage Rates Keep You From Exploring Your Options
I understand why buyers are frustrated with interest rates. The cost of borrowing money has changed significantly over the past several years, and affordability remains a real concern. But that doesn't mean every opportunity in today's market is a bad one.
Sometimes the best deal isn't the home with the lowest advertised price. It might be a brand-new home where the builder is willing to reduce the price, contribute toward closing costs, or help secure a more affordable mortgage payment. The key is knowing where to look, understanding what you're being offered, and making sure the numbers work for your situation.
If you're thinking about buying a home in Maryland, Pennsylvania, Virginia, or West Virginia, don't overlook new construction. Our team can help you explore available properties, compare builder incentives, and determine whether one of these opportunities makes sense for you.
The deals are out there. You just need to know where to find them.
Thinking of Buying? Thinking of Selling? Let’s Talk.
© Rob Krop Team
All Rights Reserved